For UK sole traders · 14 min read
Is a website tax deductible? The rule HMRC uses
Nearly every source calls a website advertising and stops. HMRC's own manual says that label settles nothing. The shop window rule, and what it means.
The answer you will find everywhere, and what is missing from it
Type the question into a search box and it comes back the same way from a dozen accountancy blogs, expenses guides and bookkeeping apps. A website is advertising or marketing. Advertising and marketing are allowable business expenses. So put the invoice through the books and set it against this year's profit. GOV.UK appears to back that up: its guidance for the self-employed, under advertising, marketing and subscriptions, lists website costs in the same short set as newspaper advertising, mailshots and free samples.
The difficulty is that HMRC's own manual, the one written for its inspectors, says that calling something advertising does not settle how it is treated. The Business Income Manual at BIM35815 quotes Lord Morris in Strick v Regent Oil Co Ltd [1965] 43TC1, to the effect that "to call such sums marketing costs is merely to apply a neutral or generic description which in no way distinguishes between payments of a capital nature and payments of a revenue nature". The manual's own version of the point is shorter. What falls to be considered, it says, is "the nature of that for which payment has been made".
So the answer to whether you can claim a website is not yes, and it is not no. It is that a website is not one cost. It is at least two costs that the tax system treats differently, and which one you are looking at is not decided by the word somebody typed on the invoice.
That matters in one situation more than any other: a sole trader on the accruals basis who has paid a single large invoice for a build and is expecting all of it to come off this year's profit. If that is you, read the whole page. If you pay a modest fee every month and nothing else, the last section will tell you plainly that there is nothing here for you to do.
Tip. This page is general information about how published HMRC guidance reads. It is not tax advice, it has not seen your figures or your circumstances, and it does not replace your accountant, who is the person who decides and signs off what goes on your return. Everything quoted below was read on GOV.UK on 25 August 2026. Tax rules change, and one of the rules on this page changed recently.
The shop window, which is the whole rule
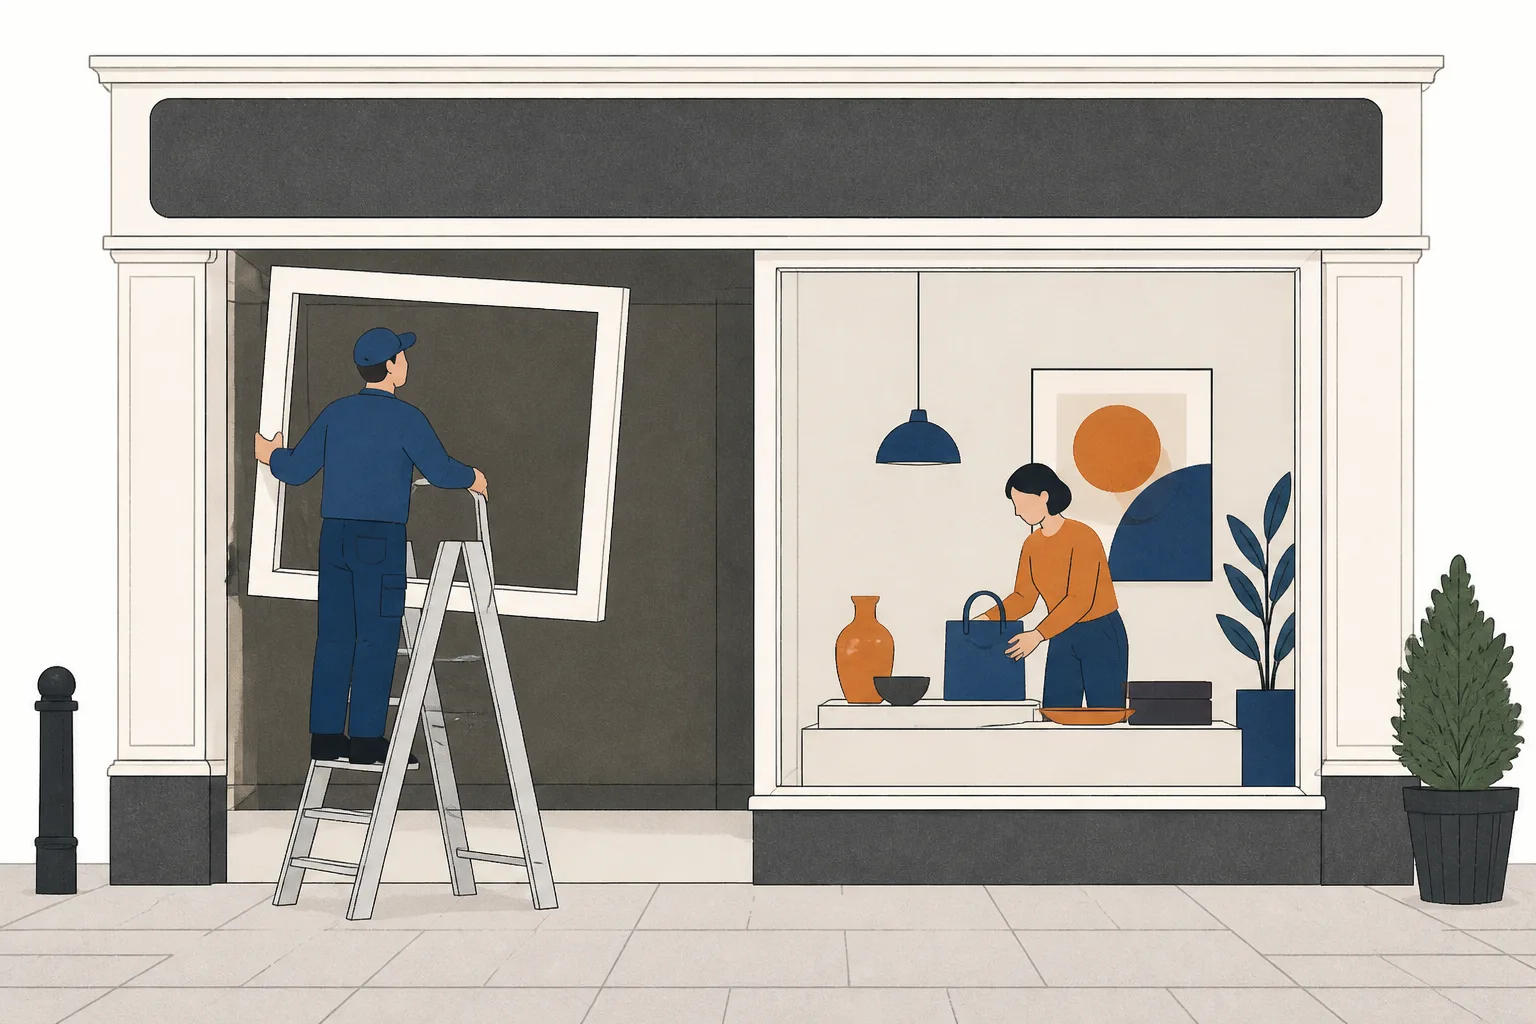
BIM35815 is headed Capital/revenue divide: computer software: costs of setting up a web site. It is a short page, it has been on GOV.UK since 2013, and it turns on two sentences that anyone who has ever fitted out a shop understands on first reading.
"The cost of a web site is analogous to that of a shop window. The cost of constructing the window is capital; the cost of changing the display from time to time is revenue."
The two words carry all the weight, so they are worth pinning down. Revenue expenditure is an ordinary running cost of trading this year, and it comes off this year's profit — which is what most people mean when they say something is deductible. Capital expenditure brings into existence something with a life beyond this year: the window, the van, the tool that will still be earning in five years. The manual states that general principle first, and points at Anglo-Persian Oil v Dale [1931] 16TC253 for the test of whether what you bought has the lifetime normally expected of a capital asset.
Applied to a website, that puts the first build on one side and everything you do to it afterwards on the other. Changing your prices, swapping in this year's photographs, adding a page for a service you have started offering — that is the display being changed. This is a better rule than the advertising label because it survives contact with the question. Nobody thinks the shopfitter's invoice and the window dresser's invoice are the same kind of cost simply because both were spent on being seen from the pavement.
Two supporting points come from the neighbouring page, BIM35810, which covers computer software generally. The first limits how hard HMRC will push the capital argument: the manual instructs that "You should not contend that software with an expected useful life of less than two years is capital". The second closes off the obvious counter-argument, that a thing you change constantly must be short-lived. It is not enough on its own. A site you edit every month is still a site you expect to have in three years.
Note. The shop window is an analogy in a manual, not a statute. It tells you how HMRC thinks about the question and how an inspector has been told to approach it. It does not do the arithmetic for your particular set of accounts, which is the job of the person who has them open.
Which side of the window each of your costs sits on
Here is the analogy laid across the things a small business actually pays for. Read the last column as how the rule reads rather than as a finding about your books, because a finding needs your books.
| What you paid for | Which part of the shop window it is | How the rule reads |
|---|---|---|
| The first build of the site, paid once | Constructing the window | Capital |
| A full replacement of the site some years later | Constructing a new window | Capital |
| A monthly or yearly platform or hosting fee | The cost of keeping the shop open | Revenue |
| Changing prices, adding photographs, a new service page | Changing the display | Revenue |
| Domain registration, renewed each year | The address, rented by the year | Revenue |
| Adding bookings or payments to a site you already have | A new fitting rather than a new display | Arguable, and worth raising |
Note. The words on the invoice decide none of this. That is the point BIM35815 makes about the word advertising, and it applies just as much to the words design, maintenance and support. What decides it is what the payment actually bought.
Capital does not mean you never get relief
The word capital makes people assume the money has vanished for tax purposes. It has not necessarily. Capital means the cost is not simply set against this year's trading profit in the ordinary way, and that a different set of rules decides what happens to it instead.
Which rules, and what they give you, depends on how you keep your accounts, on what precisely you bought, and on facts about your business that a web page cannot see. So this page is not going to name a relief and tell you it applies to your build. That is the sort of confident guess that ends with somebody amending a return.
What is worth doing beforehand is separating two claims that get muddled together. Somebody telling you a website is advertising and therefore fully deductible has told you something HMRC's manual specifically says is not the test. Somebody telling you that on your basis of accounting the whole payment is allowable in the year you paid it may be completely right, for a reason that has nothing to do with the word advertising. The next section is that reason, and for most sole traders it is now the more important half of the page.
The cash basis, which changed the question in 2024
For tax years beginning on or after 6 April 2024, the cash basis is the default way a sole trader works out trading profit. BIM72005 puts it in one line: "Use of the cash basis is the default method of accounting unless an election is made to calculate profits in accordance with generally accepted accounting principles." Before that it was something you opted into. Now it is something you would have had to opt out of, so unless you or your accountant made that election, there is a fair chance you are on it without ever having picked it.
That matters more than anything else here, because the cash basis handles capital spending differently. BIM72035 states that in calculating the profits of a trade on the cash basis, capital expenditure is treated as an allowable business expense — and then gives a list of things that are excluded from that treatment.
Two of the exclusions are worth reading twice if you have a website in mind. One takes out an asset whose useful life will not end, or will not decline in value by 90% or more, within 20 years. The other takes out what the manual calls a non-qualifying intangible asset, and BIM72037 defines that from the other direction: "An intangible asset is non-qualifying unless it has a fixed maximum duration and will cease to exist within 20 years of the date the capital expenditure was incurred."
Now the honest part, which is why this page ends in a conversation rather than an answer. BIM35815 is written in the language of the accruals basis and says nothing at all about the cash basis rules that arrived for 2024-25. HMRC has not published a page that walks a sole trader from one to the other for the specific case of a website. Fitting the two together for a real set of books is a professional judgement about a real business, and anybody on the open web handing you a flat answer to it, this page included, would be telling you more than the guidance says.
So take it to your accountant as five short questions rather than as a general worry. It is the only part of this page that changes what happens on your return.
- Which basis am I on for this tax year, cash or accruals, and did anybody make an election.
- On that basis, how are you treating the build invoice, and in which year does it land.
- Is any part of what I paid capital in your view, and if it is, what happens to it.
- Does the answer change if I replace the site rather than change the one I have.
- Is there anything about how the invoice is worded that makes your job harder next time.
Note. Being on the cash basis is not automatically better and this is not a recommendation to be on it. It is the default, which is a different thing, and there are businesses for which the accruals basis is the right answer. That choice is a much bigger conversation than a website and it should not be made because of one.
Ask for an itemised invoice, before the money moves
The most useful thing you can do about any of this costs nothing and happens before you pay. Ask for the invoice to be itemised.
An invoice that reads Website and then a single total hands your accountant a lump with no seams in it, and the safe treatment of a lump is usually the least generous one available. One that separates the build from the words, the words from the photographs, the domain from everything else and the monthly fee from all of it lets somebody put each line where it belongs. If you are the person writing the invoice rather than paying it, the same applies from your side, and it costs you a minute.
The same discipline applies after launch. Changes dated and described in a sentence each are evidence; six months of them billed as one line reading support is a question mark.
- The build itself, on its own line, with the date the site actually went live.
- Writing the words and taking the photographs, listed separately from the build.
- Domain registration, with the period it covers written on it.
- Hosting or the platform fee, by month or by year, with the dates.
- Anything paid after launch, dated and described well enough to tell a change from a replacement.
Note. GOV.UK is exact about how long this paperwork has to survive: "You must keep your records for at least 5 years after the 31 January submission deadline of the relevant tax year." A build invoice from this year is therefore something you are still holding in the early 2030s, which is an argument for filing it somewhere better than the email it arrived in.
Do not buy a website because of the tax
Relief reduces a cost by whatever rate you pay tax at. It does not refund the cost and it never turns money spent into money gained. A website you did not need is not made sensible because part of it comes off your profit, and a more expensive one is not a better decision than a cheaper one because there is more of it to deduct. All of that is obvious written down and considerably less obvious in December, with somebody selling.
The same warning applies to a consequence of the rule that this page has an obvious interest in, so it gets said here rather than anywhere it could be leaned on. A large one-off payment for a build is the window being constructed; a fee paid every month for a site that is hosted, changed and kept running is an ordinary cost of trading. That is where the line happens to fall and it is not a reason to buy a website one way rather than another. It cuts both ways, too. If a one-off build from an agency is the right thing for your business, the possibility that part of it is capital is a thin reason to avoid it.
Here is the part that is unhelpful to us. For a great many sole traders, this entire distinction moves the final figure by less than the value of the afternoon spent worrying about it. If you pay a modest monthly fee, you are on the cash basis, and your accountant has never once raised it, there is nothing on this page for you to act on. Keep the invoices, hand them over, and go and quote for something.
It bites in one place, and knowing which place is most of the value here. A single large payment for a build, on the accruals basis, in a year where you were counting on it to reduce your profit. That is where being wrong costs you something real, either as a tax bill you had not budgeted for or as a return you have to go back and amend.
Four things this page is not about
The page is about income tax on the trading profits of a UK sole trader, and it stops there on purpose. Four boundaries, so nobody carries an argument somewhere it does not go.
- VAT. Whether a VAT-registered business can recover the VAT on a website is a separate question under separate rules, and nothing above touches it.
- Limited companies. A company pays corporation tax and its guidance sits in a different manual. The underlying capital and revenue divide is the same idea, but do not carry the rest of this across without checking.
- Anywhere outside the United Kingdom. Australia, Ireland and everywhere else have their own rules and their own thresholds, and none of this transfers.
- Your figures. Nothing here has seen them, and the whole point of the page is that the answer depends on things it cannot see.
The pages this was read from, so you can check them
- BIM35815
- Capital/revenue divide: computer software: costs of setting up a web site — the shop window, and the point about the advertising label
- BIM35810
- Computer software: general considerations — the two-year point
- BIM72005
- Cash basis: overview, tax years from 6 April 2024 — the default wording
- BIM72035
- Cash basis: expenses: capital expenditure — treatment and exclusions
- BIM72037
- Cash basis: intangible assets — the definition of non-qualifying
- GOV.UK
- Expenses if you are self-employed, under advertising, marketing and subscriptions — where the common answer comes from
- Read on
- 25 August 2026
Common questions
- So is a website tax deductible or not?
- Part of it almost certainly is, and the part that is not straightforwardly deductible is not necessarily lost either. Hosting, a monthly fee, the domain and changing what is on the site all read as revenue. The original build reads as capital under BIM35815, and what happens to a capital cost depends on your basis of accounting and your circumstances, which is a question for your accountant rather than for a web page.
- My accountant says to put it through as advertising. Are they wrong?
- Probably not wrong about the outcome, and they have your accounts in front of them, which nobody writing on the internet does. The narrow point here is that the word advertising is not the reason, because HMRC's manual says the label distinguishes nothing. If the answer turns out the same, it is the same for a different reason, and that reason is more likely to be the cash basis than the label.
- Where does the domain name sit?
- A domain is registered for a period and renewed, so it reads as a recurring cost of trading rather than as construction of an asset. Put the registration on its own invoice line with the period it covers and it will be obvious to whoever files it.
- What about the money I spent on photographs and on having the words written?
- They were bought alongside the build, which is why they land on the same invoice, but they are not obviously the same kind of cost and should be itemised separately so somebody can decide. It is the clearest reason not to accept a single line reading Website: one line forces one treatment on to several different things.
- I paid for the site in one tax year and launched it in the next. Which year does it belong to?
- That depends on your basis. The cash basis records money when it moves; the accruals basis records a cost when it is incurred, and there is a further question about when an asset is brought into use. Those have real answers and this page is not going to guess at yours. Note both the payment date and the launch date on the paperwork, and let your accountant apply the right one.